If you have Medicare or are about to enroll, you've probably heard about Original Medicare and Medicare Advantage.
And it's normal to have questions.
Are they the same? Which one lets you keep your doctors? Which one includes drugs? What happens with costs when you need medical care?
The difference is simpler to understand than it seems.
Original Medicare and Medicare Advantage are two different ways to get your Medicare benefits. Knowing how each one works can help you ask better questions before choosing your coverage for 2027.
First: what are Medicare Parts A, B, C, and D?
Before comparing the two options, it's worth understanding what each part means.
Part A: helps cover hospital stays and certain related services.
Part B: helps cover medical and outpatient services, such as doctor visits, tests, certain medical equipment, and preventive services.
Part C: is another name for Medicare Advantage. These are plans offered by private companies approved by Medicare.
Part D: helps cover prescription drugs.
Now we can better understand the two main ways to get your coverage.
What is Original Medicare?
Original Medicare is made up of Part A and Part B.
With this option, you get your benefits directly through Medicare.
One of its main features is the freedom to choose providers. You can go to any doctor or hospital in the United States that accepts Medicare.
Original Medicare, however, doesn't automatically include prescription drug coverage. If you want that coverage, you can usually enroll separately in a Part D plan.
You can also consider a Medicare Supplement policy, known as Medigap, to help with certain costs Original Medicare doesn't pay.
What is Medicare Advantage?
Medicare Advantage, also known as Part C, is another way to get your Medicare benefits.
Instead of getting your Part A and B benefits directly through Original Medicare, you get them through a plan offered by a private company approved by Medicare.
To enroll in Medicare Advantage, you must have both Part A and Part B.
Most of these plans also include drug coverage, and many offer extra benefits Original Medicare usually doesn't include, such as dental, vision, or hearing services.
Benefits and costs are not the same in every plan.
That's why it's important to review the specific plan available where you live.
Original Medicare vs. Medicare Advantage: quick comparison
| Original Medicare | Medicare Advantage | |
|---|---|---|
| Who manages your benefits | Medicare | A private company approved by Medicare |
| Part A and Part B | Yes | Yes, through the plan |
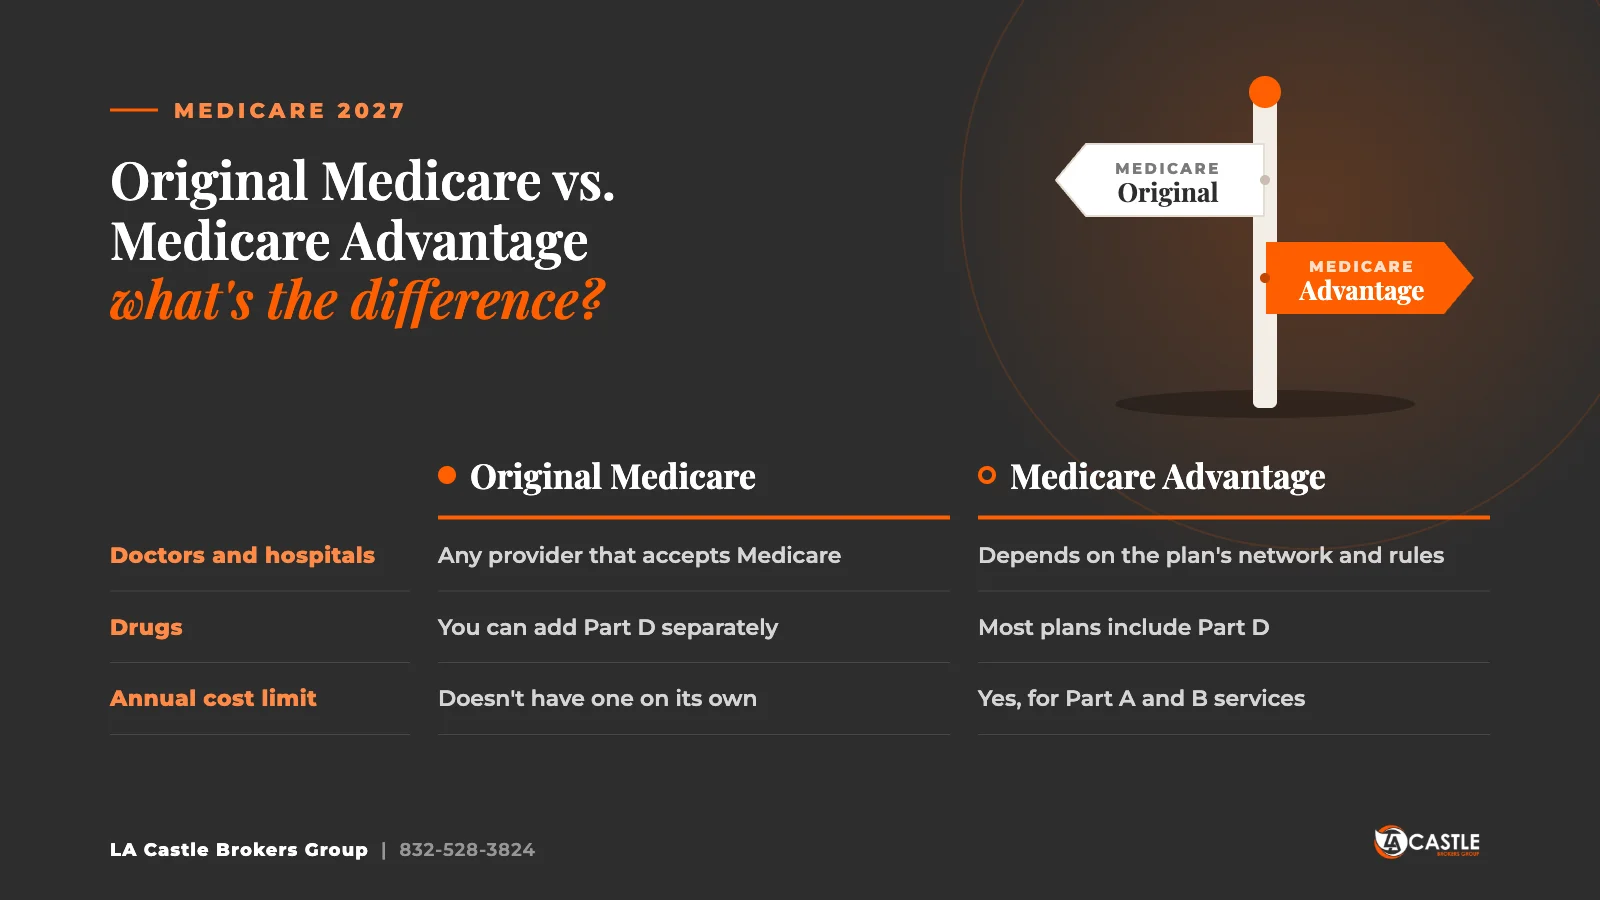
| Doctors and hospitals | Any provider that accepts Medicare | Depends on the plan's network and rules |
| Drugs | You can add Part D separately | Most plans include Part D |
| Extra benefits | Generally limited | Many plans offer extra benefits |
| Annual limit on out-of-pocket medical costs | Original Medicare alone doesn't have one | Yes, for services covered by Parts A and B |
| Medigap | You can buy it if you meet the applicable requirements | Doesn't work with Medicare Advantage |
But a table doesn't tell the whole story.
Let's look at some differences that can affect your decision.
Can I keep seeing my doctors?
This is one of the most important questions before choosing coverage.
With Original Medicare, you can see doctors and hospitals in the United States that accept Medicare. You're not limited to a private plan's provider network.
With Medicare Advantage, the rules depend on the plan.
Some plans work with a specific network of doctors, specialists, and hospitals. Depending on the type of plan, getting care outside that network may cost you more or may not be covered, except in certain situations.
That's why, before enrolling in a Medicare Advantage plan, looking at its benefits isn't enough.
It's also worth asking:
Is my doctor in the network?
Is my hospital in the network?
Are my specialists in the network?
Those questions can matter much more than an extra benefit shown in a brochure.
Which one costs less?
There's no single answer for everyone.
With Original Medicare, you have certain costs set by Medicare.
For 2027, some of those amounts are still projections and may change when CMS publishes the final figures. The standard Part B premium is currently projected at about $209.50 a month, with an annual deductible of about $292.
After the deductible, you usually pay 20% of the Medicare-approved amount for many services covered by Part B.
In addition, Original Medicare alone doesn't set an annual limit on out-of-pocket costs.
Medicare Advantage works differently.
Each plan sets its own costs within Medicare's rules. You can find plans with a $0 additional monthly premium and others that charge a premium.
But here's something important:
A $0 premium doesn't mean free medical care.
You can still have copays, the percentage you pay after the deductible (coinsurance), and other costs when you use certain services.
Medicare Advantage plans also have an annual limit on what you pay out of pocket for services covered by Parts A and B.
That's why comparing only the monthly premium can give you an incomplete picture.
What about drugs in 2027?
If you take prescription drugs regularly, this part deserves special attention.
With Original Medicare, you can enroll separately in a Part D drug plan.
Most Medicare Advantage plans already include drug coverage, although there are exceptions.
For 2027, some important Part D numbers are already set.
The maximum allowed annual deductible will be $700, although a plan can set a lower deductible.
There will also be an annual limit of $2,400 in out-of-pocket costs for drugs covered by Part D.
But knowing those numbers doesn't tell you which drug plan may work best for you.
Why?
Because each plan can cover different drugs and have different pharmacies, costs, and rules.
A good comparison should start with something much more personal:
What prescription drugs do you take today?
Does Medicare Advantage include extra benefits?
Many Medicare Advantage plans offer benefits Original Medicare usually doesn't cover.
Depending on the plan, they may include dental, vision, hearing, and other extra benefits.
But here, too, it pays to be careful.
Not every plan offers the same benefits or works the same way.
A benefit that looks attractive may have limits, participating providers, or specific rules.
That's why it's worth looking at the whole plan and not choosing based only on one extra benefit.
So, Original Medicare or Medicare Advantage?
This is probably the question we hear most.
And the answer depends on the person.
Two neighbors of the same age may need completely different coverage.
One may travel often and want more flexibility to choose doctors. The other may prefer a plan that brings different benefits and services together in a single plan.
You also need to consider your doctors, hospitals, drugs, budget, and health care needs.
That's why, instead of starting with:
"Which plan is best?"
it may be more useful to ask:
"Which option works best for my situation?"
When can I change my coverage for 2027?
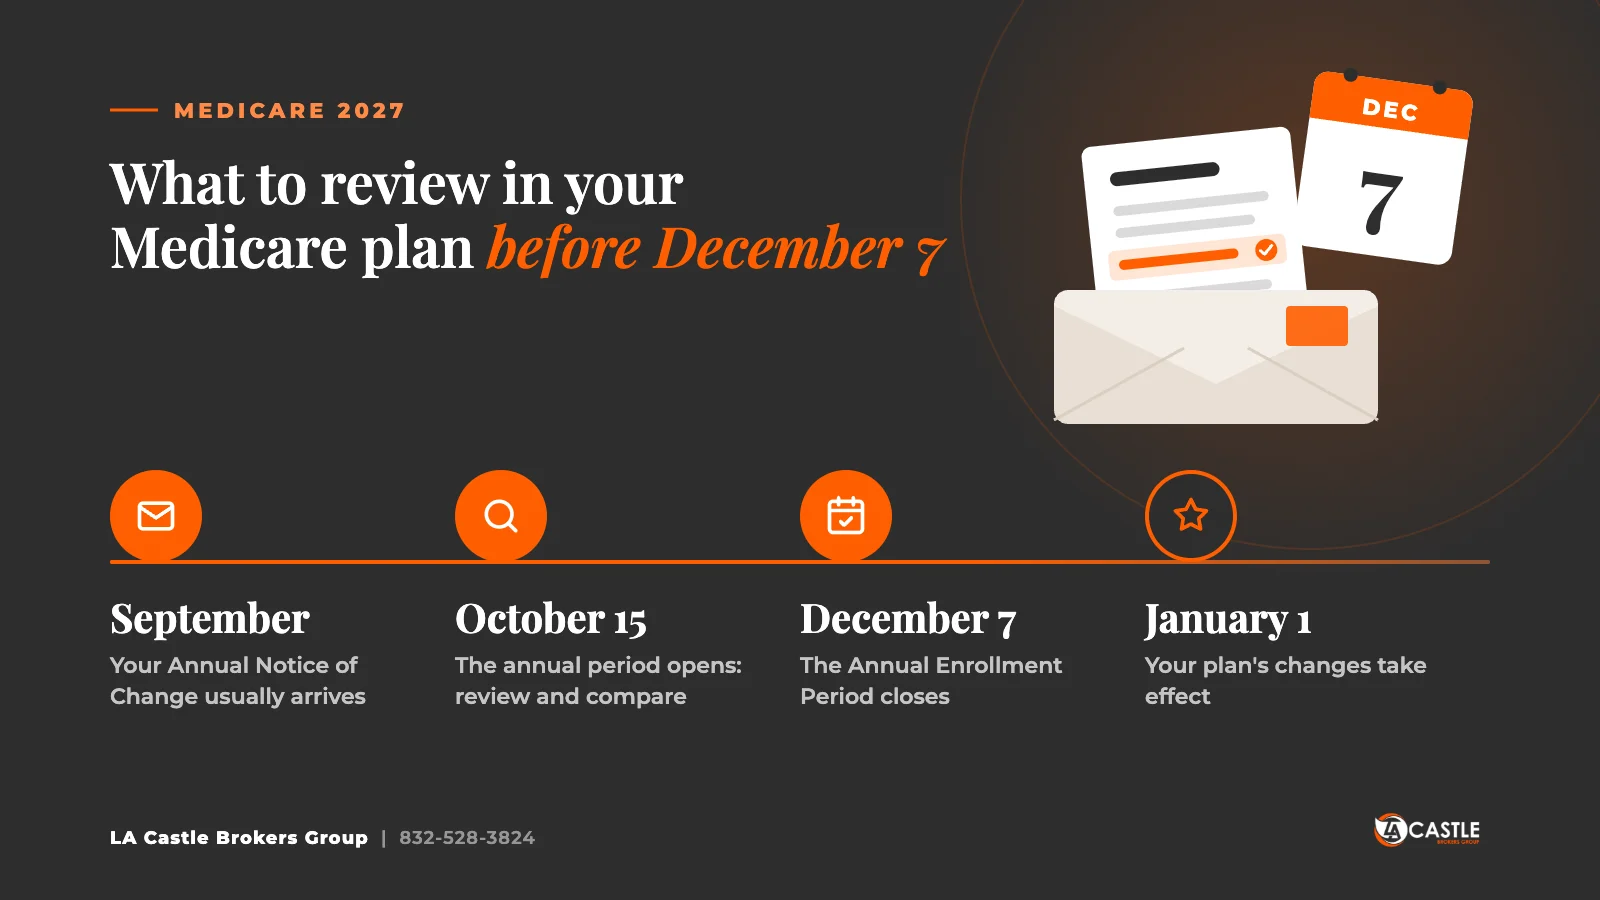
The Medicare Annual Enrollment Period runs from October 15 to December 7, 2026.
During this period, you can review your coverage and make certain changes for next year.
Changes made during this period usually start on January 1, 2027.
There is also the Medicare Advantage Open Enrollment Period, from January 1 to March 31, for people who are already enrolled in Medicare Advantage. During that period, there are specific options to change coverage.
In addition, some personal situations may give you the right to a Special Enrollment Period outside those dates.
Before choosing for 2027, review these four things
You don't need to become a Medicare expert to review your coverage.
But it does help to know four things:
- Your doctors: do they participate in the plan you're considering?
- Your drugs: are they covered, and how much could they cost you?
- Your costs: what would you pay when you actually need to use your coverage?
- Your needs: which benefits really matter to you?
A plan can look excellent on paper and still not be right for your situation.
Need help comparing your Medicare options for 2027?
Understanding the difference between Original Medicare and Medicare Advantage is a good start.
The next step is to look at how those differences apply to your situation.
Your doctors, drugs, coverage needs, and the plans available where you live can change the comparison.
At LA Castle Brokers Group, we can help you review those factors, explain your options in plain language, and compare the available plans so you can make an informed decision.
Or call us at 832-528-3824.
Frequently asked questions
Can I have Original Medicare and Medicare Advantage at the same time?
They don't work as two primary coverages at the same time. Medicare Advantage is another way to get your Part A and B benefits. To have Medicare Advantage, you must stay enrolled in both parts.
Does Medicare Advantage always cost less than Original Medicare?
Not necessarily. Costs depend on the plan, the services you use, and your situation. A low or $0 monthly premium doesn't mean you won't have costs when you use your coverage.
Does Medicare Advantage include drug coverage?
Most Medicare Advantage plans include Part D drug coverage, but there are exceptions. Always review the specific plan.
Can I use Medigap with Medicare Advantage?
No. Medigap is designed to supplement Original Medicare and doesn't work with Medicare Advantage.
Do I have to change my Medicare plan every year?
Not necessarily. But it's a good idea to review your coverage every year because costs, benefits, covered drugs, and provider networks can change.
Important notice: LA Castle Brokers Group is an independent agency/broker licensed to offer Medicare products. We are not a government agency and are not affiliated with the United States government. Plan availability, benefits, and costs depend on the area and the specific plan.
2027 information: Some Medicare Part A and Part B costs mentioned in this article are projections and are subject to the final amounts published by CMS. The Part D parameters identified for 2027 reflect official information available for that year.
LA Castle Brokers Group — Houston, Texas. We speak English and Spanish.