The question almost no one asks in time
The right amount of life insurance isn't a magic number: it's what your family would need to keep going if you were gone tomorrow. In this guide, we show you how to figure it out yourself, with pen and paper, in about 15 minutes.
It's a conversation many families put off, and the numbers show it. According to the 2025 Insurance Barometer Study by LIMRA and Life Happens, only 40% of Hispanic Americans have life insurance, the lowest rate of any ethnic group. In the 2024 edition, 46% of Hispanic families said they would face financial hardship in less than six months if the primary wage earner died.
What's most revealing is why they don't have it. In that 2024 edition, more than 7 in 10 Hispanic Americans (72%) overestimated the cost of term life insurance. The problem is almost never a lack of love or responsibility: it's a lack of clear information.
Why "10 times your income" falls short
The 10-times-your-income rule is a good starting point, but it isn't a plan. If you earn $50,000 a year, the rule says you need $500,000 in coverage, and that's where the analysis ends.
The problem is what that rule doesn't look at:
- Your actual debts. Two families who earn the same can owe very different amounts.
- Your mortgage. A house that's almost paid off isn't the same as one bought two years ago.
- Your kids. A baby isn't the same as a teenager about to finish high school.
- What you already have. Savings or life insurance through work reduce what you still need.
- The parent without a paycheck. For a stay-at-home mom or dad, 10 times zero is zero. And that result is wrong.
That's why we use a method that starts from your family's real obligations, not just your salary.
The DIME method, step by step
DIME stands for Debt, Income, Mortgage, and Education: four things your family would have to cover without you. Add up all four and you have your starting point.
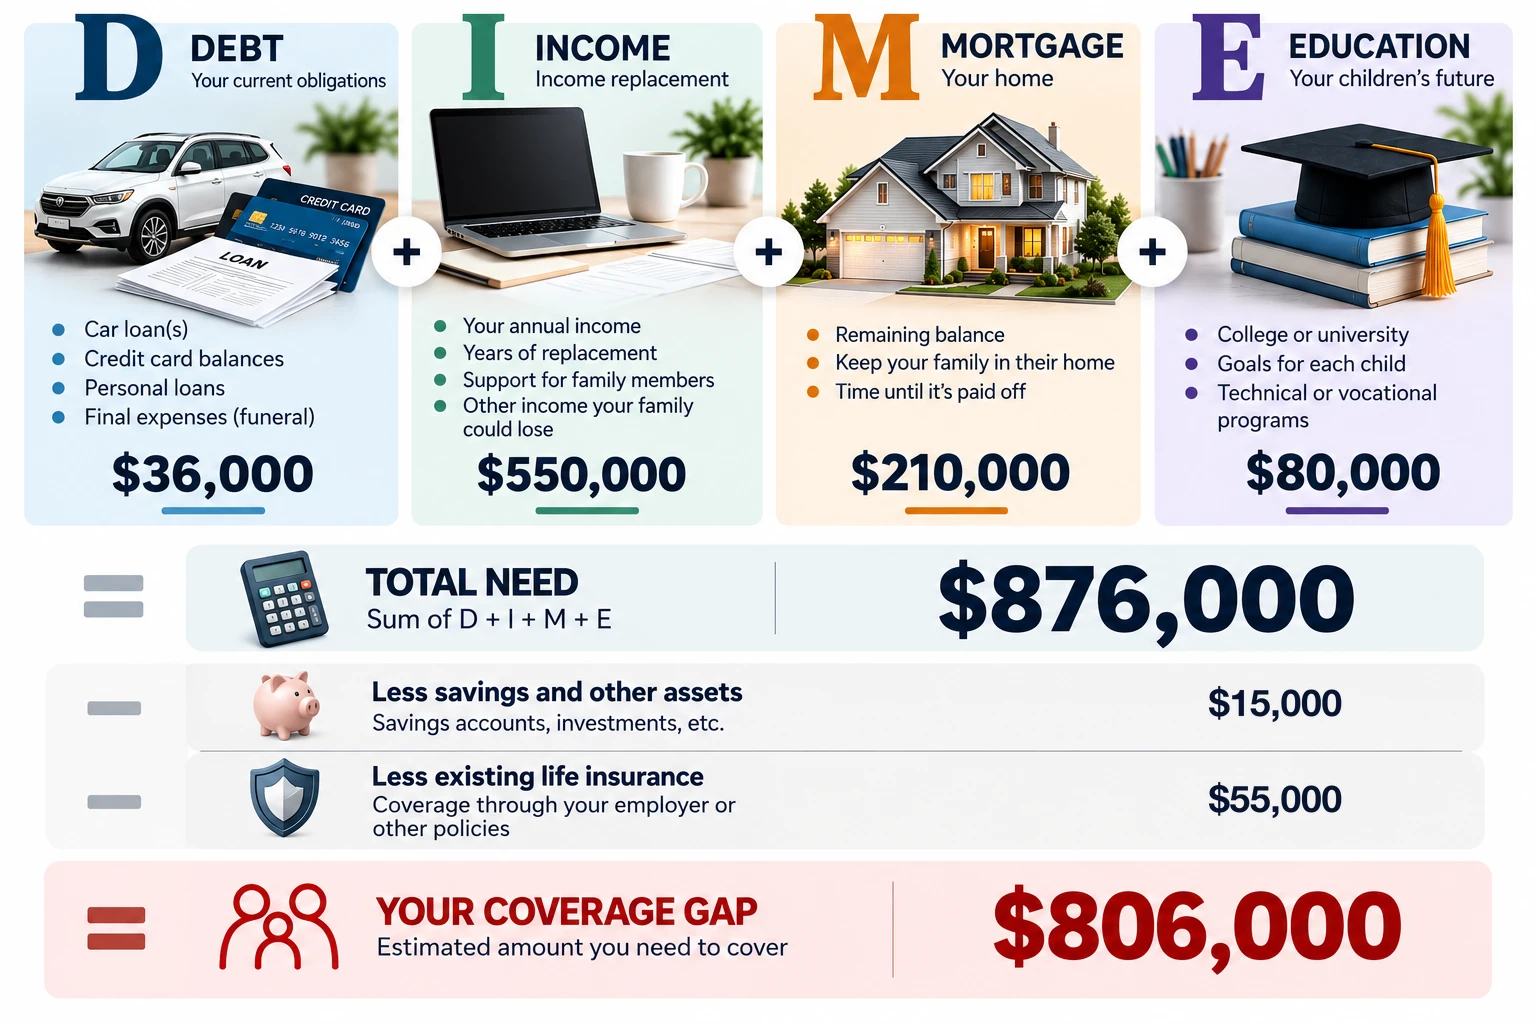
To make it clear, let's use an example. Carlos is 38 and lives in Katy with his wife, Andrea, and their two kids, ages 6 and 10. He earns $55,000 a year.
D: Debt and final expenses
Add up everything you owe except the mortgage: car loan, credit cards, personal loans. Then add funeral costs. According to the National Funeral Directors Association, the median cost of a funeral with a casket and burial was $8,300 in 2023, not counting the cemetery or headstone.
Carlos owes $18,000 on his car and $6,000 on credit cards, and he estimates $12,000 for the funeral, including the cemetery. Total D: $36,000.
I: Income
Multiply your annual income by the number of years your family would need that support. A common reference point is to cover the years when your kids depend most on your income.
Carlos chooses 10 years: $55,000 × 10. Total I: $550,000.
M: Mortgage
Write down what's left to pay on the house, not the original price. The idea is that your family can stay in their home without that burden.
Carlos has $210,000 left. Total M: $210,000.
E: Education
Decide how much you want to leave for each child's education after high school. There's no right answer here: it's a family goal.
Carlos and Andrea choose $40,000 per child. Total E: $80,000.
The result
| Component | Carlos |
|---|---|
| D: Debt and final expenses | $36,000 |
| I: Income (10 years) | $550,000 |
| M: Mortgage | $210,000 |
| E: Education | $80,000 |
| DIME total | $876,000 |
Compare: the 10-times-income rule would have told him $550,000. With DIME, Carlos sees that the rule would have left him short by more than $300,000.
What traditional DIME misses
Online calculators were designed for an average family. In many Houston families, responsibilities reach further, and your calculation should reflect that.
Money you send to family
If you send money every month to your parents or siblings, here or in another country, that support would also disappear with you. Multiply what you send each year by the number of years you'd want to cover it.
If Carlos sends his mom $300 a month, that's $3,600 a year. Over 10 years, that's $36,000 more: if he decides to include it, his DIME total goes from $876,000 to $912,000. To keep the example simple, we'll stick with the basic total of $876,000.
Parents who live with you
Many families care for a grandparent or another older relative at home: medications, appointments, transportation. If you cover those expenses, include them under Income.
When both of you work
A common mistake is to calculate only for the higher earner. If Andrea also works, her income supports part of the household, and she needs her own DIME calculation and her own policy.
When one of you stays home
Here's the costliest mistake. In the formula, the income line for the person without a paycheck shows zero, and it looks like they don't need insurance.
The reality is different. If the person who takes care of the home and the kids is gone, the family would have to pay for child care, transportation, meals, and cleaning. Insure.com's annual index estimated that a mother's unpaid work was worth $145,235 a year in 2025. Even if your number is lower, it's never zero.
To calculate it, estimate how much it would cost each year to pay someone for those tasks and use that as if it were income.
Last step: subtract what you already have
The DIME total is what your family would need. What you still need is that total minus what you already have available: savings, investment accounts, and existing life insurance.
Carlos has $15,000 in savings, plus life insurance through his job equal to one times his salary: $55,000.
| Item | Amount |
|---|---|
| DIME total | $876,000 |
| Minus savings | -$15,000 |
| Minus insurance through work | -$55,000 |
| What he still needs | $806,000 |
A word of caution about insurance through work
The insurance your employer provides helps, but it has an important limit: it usually ends when you leave that job. Many plans give you a short window, often 31 days, to convert it or take it with you as an individual policy, almost always at a higher premium. If Carlos changes jobs and doesn't use that option, that $55,000 disappears, and what he still needs rises to $861,000.
That's why we recommend seeing insurance through work as a supplement, not as your main plan.
When to run the numbers again
Your number isn't forever. It changes when your life changes, and ideally you should review it whenever any of these things happen:
- You get married or divorced.
- A child is born or joins the family.
- You buy a home or refinance your mortgage.
- You change jobs, or your income goes up or down significantly.
- You start supporting your parents or another relative.
- You open a business or take on a large debt.
If none of that has happened, a review every two or three years is enough. At LA Castle Brokers Group, we do it with our clients at no cost, because coverage that was well calculated five years ago may fall short today.
Your next step
You now have the tool to calculate your number. If questions came up along the way, or you'd like us to review the calculation with you and your partner, we'll do it at no cost at LA Castle Brokers Group. First you understand, then you decide.
Or call us at 832-528-3824.
Frequently asked questions
Would my family have to pay taxes on the insurance money?
Generally, no. According to the IRS, money a beneficiary receives because of the insured person's death doesn't count as taxable income. The most common exception: if that money earns interest before it's paid out, the interest does have to be reported. That's why, in most cases, your DIME calculation doesn't need to be inflated to cover taxes.
How much does an $800,000 policy cost?
It depends on your age, your health, the type of policy, and the number of years of coverage. Many people imagine it costs more than it really does, so it's worth getting a quote with your own information. Even so, any quote is an estimate: the final premium is set by the insurance company after it reviews your application and your health.
Term or permanent?
DIME needs such as the mortgage or raising your kids usually have an end date; that's what term life insurance is for: it covers a fixed number of years, costs less, and ends when the term is over, and renewing it afterward usually costs considerably more. Other needs last a lifetime, such as final expenses or leaving an inheritance; that's what permanent insurance is for, and it costs more because it doesn't expire. Many families combine the two.
Can I have more than one policy?
Yes. It's common to have a large policy for 20 or 30 years while the kids grow up, and a smaller one that lasts your whole life. If you already have a policy and are thinking about replacing it, don't cancel it before the new one is approved and in force: a new policy is priced based on your age and health today, and the insurance company gets a new period in which it can review your application. Often, adding coverage makes more sense than replacing it.
Can I name my minor children as beneficiaries?
You can, but in Texas it isn't the best approach if you do it without planning ahead. The insurance company won't pay the money directly to a minor. If you haven't named a custodian or a trust and the amount is more than $25,000, the money usually ends up held under court supervision, or a legal guardian has to be appointed, which takes paperwork, bonds, and time. There are simple ways to avoid this, such as naming a custodian under the Texas Uniform Transfers to Minors Act (TUTMA) or setting up a trust. To choose the best option, talk to an estate planning attorney.
Can I apply for life insurance if I don't have a Social Security number?
Some insurance companies accept applications with an ITIN instead of a Social Security number. Each company has different requirements, such as a valid ID, a U.S. address, and, in many cases, a specific immigration status or visa type. An independent agent can tell you which ones accept cases like yours; approval always depends on the insurance company's review.
Disclaimer. The examples in this article are for illustration only. Any premium is an estimate: the final cost, coverage, and approval depend on your age, your health, and each insurance company's review.
Sources:
- LIMRA, Hispanic Americans and Life Insurance: Bring Family to the Conversation (Insurance Barometer 2025)
- LIMRA, Hispanic Americans Report Greatest Life Insurance Need (Insurance Barometer 2024)
- National Funeral Directors Association, 2023 NFDA General Price List Study
- Insure.com, The Mother's Day Index (2025)
- IRS, Life insurance & disability insurance proceeds
- Western & Southern, Group Life Insurance Conversion & Portability Guide
- NerdWallet, How Much Life Insurance Do I Need?
- Texas Estates Code, Chapter 1355, Payment of Certain Claims Without Guardianship, and Texas Property Code, Chapter 141, Transfers to Minors (TUTMA)
- Nationwide, Life insurance for foreign nationals